Executive Summary
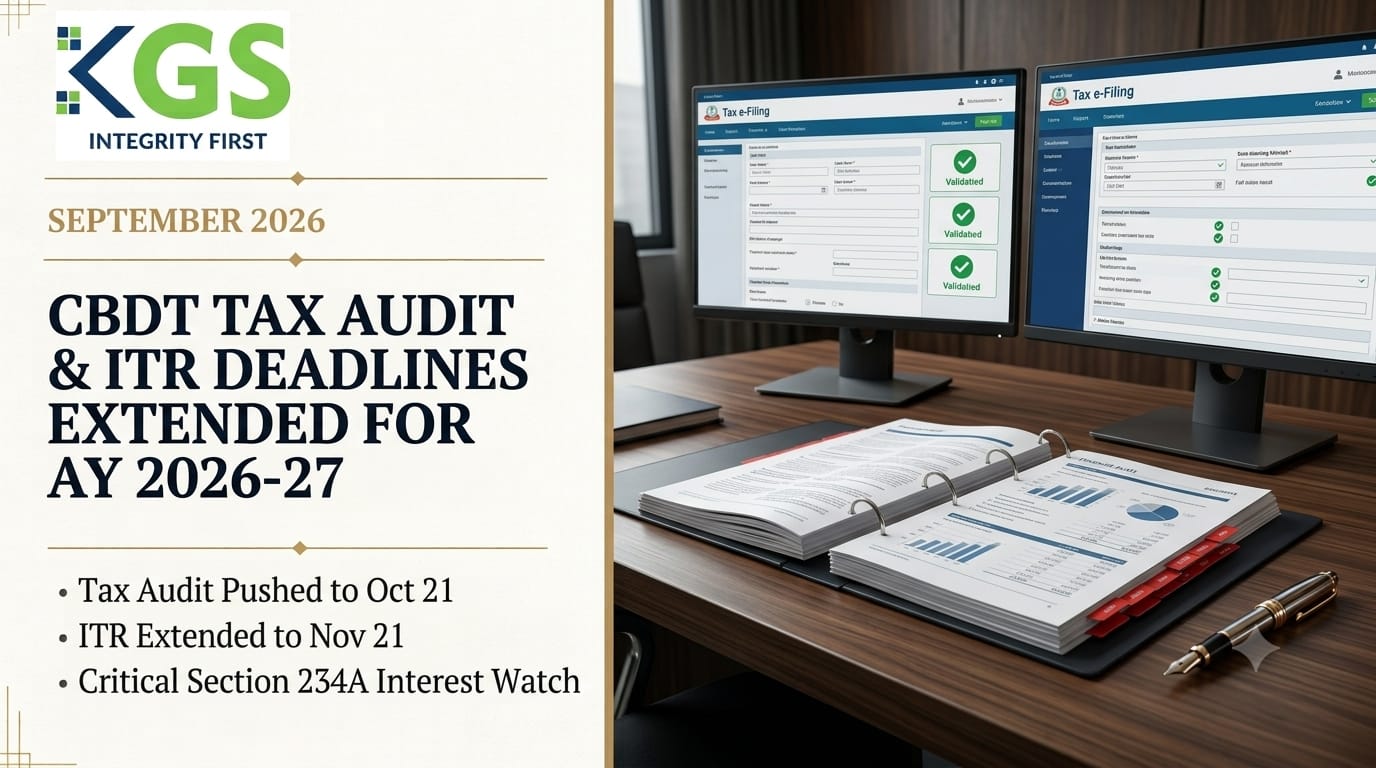
The Central Board of Direct Taxes (CBDT) has issued Circular No. 07/2026, extending the statutory due dates for filing tax audit reports and income tax returns for Assessment Year 2026-27. The deadline for submitting tax audit reports under the Income-tax Act, 1961, has been extended to October 21, 2026, while the corresponding corporate and audited return filing deadline has been shifted to November 21, 2026. This extension relieves operational pressure on businesses, accounting professionals, and tax advisors managing concurrent corporate compliance obligations.
Background
Under Section 139(1) of the Income-tax Act, 1961, taxpayers required to get their accounts audited must submit their audit reports by September 30 and corporate/audited tax returns by October 31 of the assessment year. Peak compliance windows often encounter technical strain, reporting backlogs, and overlapping deadlines with other corporate and indirect tax frameworks. In response to professional representations regarding administrative bottlenecks and system transition needs, the CBDT exercised its statutory powers under Section 119 to ease the filing burden.
What Has Changed
Particulars Earlier Statutory Position Revised Position (Circular No. 07/2026)
Tax Audit Report Submission (Form 3CA/3CB-3CD) September 30, 2026 October 21, 2026
Furnishing Return of Income (Audited Assessees) October 31, 2026 November 21, 2026
Key Provisions
• Audit Report Timelines: The due date for obtaining and furnishing audit reports under any provision of the Income-tax Act, 1961, for the previous year relevant to AY 2026-27 is extended to October 21, 2026.
• Return Filing Timelines: The corresponding due date for furnishing the Return of Income under Section 139(1) for entities subject to tax audit is extended to November 21, 2026.
• Interest Implications: The extension does not automatically waive statutory interest under Section 234A if taxes remain unpaid beyond the prescribed statutory liability thresholds.
Applicability
• Covered Entities: Assessees whose accounts are required to be audited under Section 44AB or other provisions of the Income-tax Act, 1961, including corporate entities, non-corporate business entities exceeding turnover thresholds, and partners of audited firms.
• Non-Covered Entities: Salaried individuals, non-audit individuals, and HUFs whose statutory deadline was July 31, 2026.
Practical Implications
• Tax & Audit: Audit teams gain approximately three weeks to conduct detailed reconciliations between financial books, GSTR-9/9C filings, and Form 26AS/AIS data.
• Internal Controls: Finance departments must maintain reconciliation trails without relaxing internal closing disciplines.
• Cash Flow Management: Taxpayers must ensure self-assessment taxes are settled early to minimize potential interest liabilities under Section 234A despite the administrative extension.
What Should We Do
• Assess applicability of the extension across legal entities and group subsidiaries.
• Finalize draft audit balances and obtain management representation letters ahead of the revised October 21 deadline.
• Compute outstanding self-assessment tax liabilities immediately and discharge them to avoid interest exposure.
• Track ICEGATE, MCA, and GST cross-reconciliations to align reported disclosures in Form 3CD.
KGS Perspective
Statutory extensions must be treated as opportunities for enhanced audit quality and documentation rigor rather than deferral of responsibility. Audit committees and CFOs should prioritize thorough variance analyses between statutory accounts and digital tax ledgers. Establishing robust review mechanisms prior to portal submission ensures zero discrepancies in electronic disclosures.
Conclusion
Circular No. 07/2026 provides necessary operational headroom for tax audits and returns for AY 2026-27. Entities should capitalize on the revised dates to file verified, verified, and reconciled audit packages well before the final dates.
Source / Regulatory Reference
• Regulator: Central Board of Direct Taxes (CBDT), Ministry of Finance
• Notification / Circular / Regulatory Reference: Circular No. 07/2026 [Dated 28 September 2026]
• Official Document Link: https://incometaxindia.gov.in
Comments
No Comments yet